Keep Your Money or Buy Care: Hybrid Long Term Care for Ages 50–70
Hybrid long-term care combines a life insurance policy or annuity with a long-term care benefit, so premiums pay for something even if care is never needed: either a death benefit for heirs or a return of premium. The trade-off is real cost upfront, usually well above traditional LTC premiums, in exchange for guarantees that don’t vanish if you stay healthy. It tends to fit buyers with liquid capital, roughly age 50 to 70, who want protection without the risk of paying decades of premiums for nothing.
TL;DR:
Hybrid long-term care policies usually require a significant upfront payment, often a lump sum or a limited-pay structure, making total costs higher than traditional LTC.
Claims are triggered by traditional criteria such as ADL dependence or cognitive impairment, but payout options typically include indemnity or reimbursement, affecting flexibility.
Costs are influenced by age, health, benefit multipliers, inflation riders, elimination periods, and payment modes, with single-pay often offering the most capital efficiency.
Hybrid policies provide guaranteed premiums and easier underwriting access, making them suitable for risk-averse buyers with liquidity who prefer certainty over maximum LTC benefits.
Tax advantages include income-tax-free benefits and favorable treatment of death benefits, but care must be taken to understand IRS limits and state regulations affecting eligibility and benefits.
Table of Contents
What Is Hybrid Long-Term Care Insurance?
Hybrid long-term care policies pair LTC coverage with either a life insurance chassis or an annuity, so the same premium dollar does double duty. Instead of buying a standalone LTC policy that pays nothing back if you never file a claim, you buy a permanent life policy or an annuity with an LTC rider attached. If you need care, the policy pays for it. If you don’t, your beneficiaries get a death benefit, or you get your money back.
Three product structures dominate the market:
Linked-benefit policies: purpose-built products combining life insurance and an LTC benefit pool in a single contract, usually funded with a lump sum or a short pay schedule.
Life insurance with an LTC rider: a standard whole life or indexed universal life policy with an attached rider that lets you accelerate the death benefit to pay for qualifying care.
Annuity-based hybrids: a fixed or fixed-indexed annuity with an LTC rider, often more accessible to buyers who wouldn’t pass life insurance underwriting.
Funding falls into three modes. Single-pay means one lump sum, which may commonly range from tens to low hundreds of thousands of dollars, that fully funds the policy on day one. Limited-pay, commonly structured as a 10-pay, spreads that same commitment over a decade of fixed premiums. Periodic or ongoing premium designs stretch payments over a longer window, sometimes for life, trading a lower annual outlay for less certainty about total cost.
Carriers market these products under names like “linked-benefit,” “asset-based long term care,” or “LTC combo” policies. The NAIC Shopper’s Guide treats these as interchangeable industry terms, but the underlying mechanics, especially the funding chassis, vary enough between carriers that reading the illustration matters more than the marketing label.
How Hybrid LTC Benefits Actually Pay Out
Claims trigger the same way they do in traditional LTC insurance: you need help with two or more activities of daily living (bathing, dressing, eating, toileting, transferring, continence), or you have a diagnosed cognitive impairment like dementia. A licensed health care practitioner has to certify the condition, and most policies require it be expected to last at least 90 days.
Where hybrids diverge from traditional LTC is in how the money moves once a claim is approved.
Indemnity payout: the insurer pays a set monthly amount regardless of your actual care expenses, and you decide how to spend it, including paying a family member as caregiver.
Reimbursement payout: the insurer pays only against submitted receipts from licensed providers, which limits flexibility but can prevent overpayment disputes.
Many linked-benefit hybrids default to indemnity, which is a meaningful advantage for families who want to compensate a relative for caregiving instead of hiring an outside agency. Traditional standalone LTC policies lean reimbursement more often, though this varies by carrier and state.
Elimination periods, the waiting window before benefits start, also work differently. A 90-day elimination period on a traditional policy means three months of reimbursed care costs before checks arrive. Hybrid designs frequently shrink this to 30 days or even zero, since the insurer already holds the full LTC benefit reserved against the underlying policy. That difference alone can mean tens of thousands of dollars in earlier cash flow during a health crisis.
Death benefit acceleration, the mechanism behind LTC riders on life insurance, works by letting you draw down the death benefit early to pay for care. If you have a $300,000 policy and use $150,000 for a two-year care episode, your heirs receive whatever is left, often reduced by more than the raw dollar amount withdrawn, depending on the acceleration formula the carrier uses. Read the rider language carefully. Some accelerate benefits dollar for dollar; others apply a discount factor.
What Hybrid Policies Cost and What Drives the Price
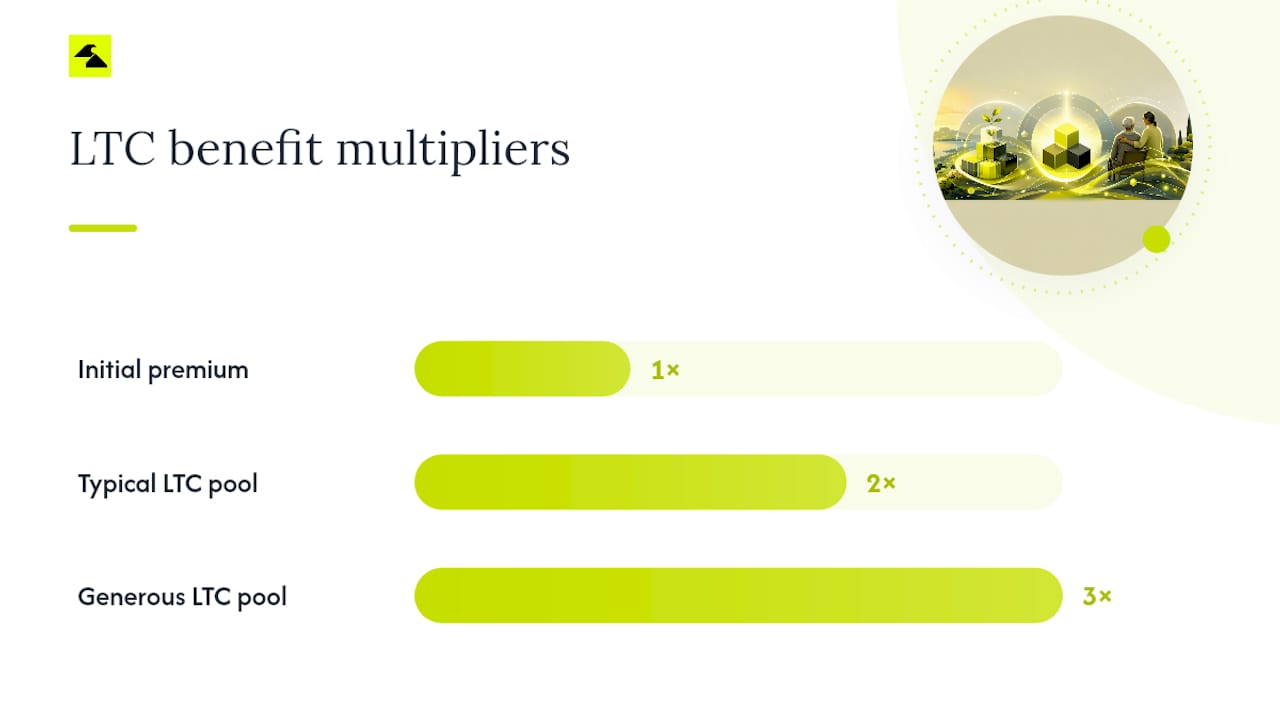
Single-pay hybrids commonly require a lump sum that can vary widely, depending on age, gender, and the size of LTC benefit pool you want. That single check can generate an LTC benefit pool worth two to three times the initial premium, plus a death benefit if care is never used. Limited-pay versions, like a 10-pay design, break that same commitment into ten annual premiums, which helps cash flow but usually costs somewhat more in total than paying it all at once.
Several variables move the price meaningfully:
Age at purchase: buying in your 50s instead of your late 60s can cut the premium substantially, since the insurer prices in more years before a likely claim.
Health rating: hybrids typically use simplified or full underwriting, and better health classes reduce cost.
Benefit multiplier and pool size: a policy that pays out three times the initial death benefit for LTC costs more than one capped at two times.
Inflation protection rider: compounding inflation protection on the LTC benefit adds meaningfully to premium but keeps pace with rising care costs over a 15 or 20-year horizon.
Elimination period: shorter waiting periods cost more.
Payment mode: single-pay is generally the most capital-efficient path per dollar of benefit, but it ties up a large sum immediately.
The real cost of single-pay funding isn’t just the check you write. It’s the opportunity cost of that capital sitting in an insurance contract instead of growing in a diversified portfolio. A useful way to think about breakeven: compare the guaranteed LTC pool and death benefit against what that same lump sum might return if invested and used to self-fund care instead. For many buyers, the guarantee is worth the spread, especially if they’re risk-averse or have a family history that raises the odds of needing care.
To manage cost without gutting the coverage, buyers often trim the inflation rider, extend the elimination period slightly, or choose a 10-pay structure instead of full single-pay to keep more capital liquid in the near term.
Hybrid vs. Traditional Long-Term Care: The Real Trade-Offs
Choosing between hybrid and traditional LTC comes down to four practical questions, not brand loyalty to either category.
Premium stability. Traditional standalone LTC insurance has a history of carriers filing for rate increases, sometimes repeatedly, years after issue. Hybrid premiums, especially single-pay and limited-pay designs, are contractually guaranteed not to rise. If premium predictability matters more to you than raw efficiency, that guarantee carries real weight.
Underwriting access. Traditional LTC underwriting can be strict, and older or health-impaired applicants get declined more often. Hybrid products, particularly annuity-based ones, frequently offer more forgiving underwriting, which matters if you’re already in your late 60s or managing a chronic condition.
Liquidity and legacy. Traditional LTC is pure insurance. If you never use it, you get nothing back. Hybrids build cash value or guarantee a death benefit, so the money isn’t lost even if care never happens, which is a major reason industry analysts point to hybrids gaining market share since around 2010.
Cost efficiency per dollar of care. Traditional LTC insurance generally delivers more pure LTC benefit per premium dollar spent, because none of that premium is subsidizing a death benefit reserve. If maximizing raw care coverage is the only goal and you’re comfortable with “use it or lose it,” traditional can be the more efficient buy.
A simple heuristic: favor hybrid if you have investable capital you’d rather not lose entirely to unused premiums, or if traditional underwriting has already turned you down. Favor traditional if your priority is maximum LTC benefit per dollar and you’re not concerned about leaving something behind for heirs. Our complete buyer’s guide to long-term care insurance walks through both categories side by side in more depth.
Tax Rules and Regulatory Guidance That Affect What You Keep
Qualified long-term care benefits paid from a hybrid policy are generally received income-tax-free, provided the contract meets the requirements of IRC Section 7702B. Death benefits paid to beneficiaries also carry favorable tax treatment under standard life insurance rules, which is part of what makes the hybrid structure attractive.
IRS per-diem limits matter for indemnity-style payouts. The IRS sets an annual cap on how much of a per-day indemnity benefit can be received tax-free without needing to document actual expenses; amounts above that indexed limit may become taxable income. Because this figure adjusts annually, check current IRS guidance before assuming your full monthly benefit is tax-free.
Premiums for tax-qualified LTC coverage, including some hybrid products, can be partially deductible as a medical expense, subject to age-based limits and the usual 7.5% adjusted-gross-income floor. Self-employed individuals may deduct LTC premiums differently, and this deduction picture connects to broader life insurance tax questions covered in our guide to life insurance tax benefits.
Beyond the IRS, a few government and regulatory sources are worth bookmarking. Medicare confirms what Medicare does not cover, custodial long-term care, which is exactly the gap hybrid and traditional LTC policies exist to fill. The ACL’s data on care needs and ASPE’s research on long-term services and supports both quantify how common a long-term care need becomes later in life, which is useful context when deciding how urgently to shop.
How to Evaluate a Hybrid Long-Term Care Offer
Comparing hybrid illustrations side by side gets confusing fast, since carriers structure guarantees differently. Work through this checklist before signing anything:
Confirm the funding mode (single-pay, 10-pay, or ongoing premium) matches your cash flow and liquidity comfort.
Separate guaranteed from non-guaranteed numbers. Ask the agent to show you the illustration at guaranteed assumptions only, stripped of any projected dividends or index credits.
Check the benefit multiplier and total LTC pool against the initial premium or death benefit.
Review the elimination period and confirm whether it’s calendar days or days of actual paid care.
Ask whether inflation protection is compound, simple, or absent, and what it costs as a percentage of premium.
Determine the claim payout model, indemnity or reimbursement, since this changes who can be paid as a caregiver.
Check the residual death benefit if the full LTC pool is exhausted by claims.
Ask about surrender charges and how long they last if you need to access cash value early.
Verify the carrier’s financial strength rating through a source like AM Best, since these are long-duration contracts that need the carrier to still be solvent decades from now.
Ask specifically what interest rate or index-crediting assumption drives any non-guaranteed projection, and what happens to your benefit pool if that assumption isn’t met. Vague answers here are the biggest red flag in hybrid shopping, right alongside rider definitions that don’t match plain-English explanations of ADL triggers.
Pro Tip: Run a simple breakeven check yourself: divide the single-pay premium by the guaranteed monthly LTC benefit to see how many months of care it would take to fully recover your premium. If that number feels unreasonably long, the pool size may be too small for the price.
Filing a Claim: What Speeds Up Approval
Claims on hybrid policies start with documentation: a licensed health care practitioner’s certification that you meet the ADL or cognitive impairment threshold, plus a plan of care. Carriers typically require this paperwork before the elimination period clock even starts, so gathering it early matters more than people expect.
Keep a running file of medical records, physician notes, and any home health assessments from the moment care needs first appear, not after you decide to file. Insurers often ask for records going back further than claimants anticipate, and delays in producing them are one of the most common reasons claims stall.
If your policy pays on an indemnity basis, confirm in writing whether you can use the funds to pay a family caregiver, and ask the carrier what documentation, if any, they still want for their own records even though reimbursement receipts aren’t required. Reimbursement-model policies demand itemized bills from licensed providers, so keep every invoice.
Designate a family member or trusted advisor as a point of contact with the insurer early on. Long-term care claims often stretch over months or years, and having one consistent person handling correspondence prevents paperwork from falling through the cracks during an already stressful period.
Does Hybrid LTC Affect Medicaid Eligibility?
Owning a hybrid long-term care policy does not, by itself, disqualify you from Medicaid, but the cash value and any accumulated benefits can factor into Medicaid’s asset tests once you’re spending down for eligibility. Life insurance with cash value counts toward Medicaid’s asset limits in most states above certain thresholds, while pure term insurance generally does not.
The bigger interaction is practical rather than legal: hybrid LTC benefits typically get exhausted before Medicaid becomes relevant, which is often the point. Using private LTC coverage first preserves your other assets and delays or avoids the Medicaid spend-down process entirely, since Medicare itself does not cover custodial long-term care, leaving Medicaid as the fallback for those who’ve depleted their resources.
Some states also run Long-Term Care Partnership programs that let you protect additional assets above Medicaid’s normal limits, dollar for dollar, based on private LTC benefits paid out. Not every hybrid policy qualifies for Partnership status, so ask specifically whether the product you’re considering is Partnership-qualified in your state if that protection matters to your planning.
Riders That Customize a Hybrid LTC Policy
Beyond the core LTC benefit, several optional riders shape how a hybrid policy performs in practice. Inflation protection, compound or simple, increases your future LTC benefit pool to keep pace with rising care costs, and skipping it is one of the more common regrets policyholders report years into a claim.
A shared care rider, available on some couples’ policies, lets spouses draw from a combined benefit pool rather than two separate ones, which can stretch coverage further if only one spouse ends up needing extended care. A return-of-premium rider guarantees your heirs or you receive back some or all premiums paid if the policy is surrendered or the insured dies without using LTC benefits, layering an extra guarantee on top of the base death benefit.
Nonforfeiture riders preserve a reduced benefit even if you stop paying premiums partway through a limited-pay schedule, protecting against a lapse wiping out the entire policy. Some carriers also offer restoration-of-benefits riders, which refill the LTC pool if you recover after a claim and go a set period without needing further care, effectively resetting the benefit for a future need.
Each rider adds cost, so prioritize the ones that address your actual risk. A single applicant has no use for a shared care rider; a couple funding one hybrid policy together might find it essential.
Regulatory Protections Buyers Should Know About
Hybrid LTC products are regulated at the state level by insurance departments, which means policy forms, rate structures, and disclosure requirements vary somewhat from state to state. The NAIC’s Shopper’s Guide sets a baseline for consumer disclosures that most states adopt, including free-look periods that let you cancel a new policy within a set window, usually 30 days, for a full refund.
State guaranty associations back a portion of insurance company obligations if a carrier becomes insolvent, though the coverage limits vary by state and shouldn’t be treated as a substitute for choosing a financially strong carrier in the first place. Checking a carrier’s rating through AM Best, Moody’s, or S&P before committing six figures to a single-pay policy is a basic due-diligence step too many buyers skip.
Most states also require insurers to offer inflation protection as an option, even if the buyer ultimately declines it, and to provide a clear outline of coverage that summarizes benefit triggers, exclusions, and elimination periods in plain language separate from the full contract. If an agent can’t produce that outline of coverage on request, treat it as a warning sign about how the rest of the sales process will go.
A Practitioner’s View on When Hybrids Make Sense
Hybrid long-term care works best as one piece of a broader capital strategy, not a standalone purchase decided in isolation, as explained in the Golden Memorial approach to long-term care planning and asset protection. At East Two West, hybrid designs get recommended when a client already has liquidity earmarked for this purpose and wants certainty over flexibility, particularly clients also using whole life insurance for Infinite Banking who want their LTC funding to complement, not compete with, that structure. The caveat worth repeating to every client: watch the non-guaranteed assumptions on any illustration, and be cautious with premium financing arrangements that can quietly erode the benefit you thought you’d locked in.
— Jib Hunt
Get a Licensed Quote on Hybrid Long-Term Care Coverage
Reading about elimination periods and benefit multipliers only gets you so far. What actually matters is how those mechanics play out in a real illustration built around your age, health, and the amount of capital you’re comfortable committing. We work with clients on Whole Life Insurance, Indexed Universal Life, and Annuities, including LTC riders and linked-benefit structures from multiple carriers.
[
Before a consultation, it helps to have a rough sense of three things: your age and general health history, the size of LTC benefit pool you’d want to protect against a multi-year care event, and how much liquidity you’re willing to commit as a single payment versus spreading it over several years. If you’re also weighing an annuity-based approach, our breakdown of the long-term care annuity option covers that path in more detail. Reach out through East Two West to schedule a consultation and get an actual quote built around your numbers, not a generic illustration.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
Is a Hybrid LTC Policy Worth It?
It depends on what you value most: guarantees or efficiency. If you have liquid capital and want to avoid losing every premium dollar if you never need care, a hybrid’s death benefit or return-of-premium feature makes the cost worth it for many buyers. If maximizing raw care coverage per dollar is your only priority, traditional standalone LTC insurance is usually more efficient.
How Much Does a Hybrid Long-Term Care Plan Cost?
Single-pay hybrid policies commonly require a lump sum that can vary widely, depending on your age, health, and the size of the LTC benefit pool you want. Limited-pay versions, like a 10-pay structure, spread that commitment over ten years instead of one payment, usually at a somewhat higher total cost. East Two West can build an illustration with your specific numbers; reach out through East Two West for current pricing.
What Is the Best Hybrid Long-Term Care Insurance?
There isn’t a single best hybrid policy, since the right structure depends on your age, health, liquidity, and whether you prioritize a death benefit, an LTC pool size, or underwriting flexibility. Working with an independent advisor who can compare linked-benefit, life-with-rider, and annuity-based designs across multiple carriers, rather than a single captive product line, is generally the better path to finding the right fit.
At What Age Should You Stop Life Insurance?
There’s no universal age to drop life insurance, since it depends on whether dependents still rely on your income, whether debts remain, and whether the policy is funding a strategy like estate liquidity or LTC coverage. Many buyers keep permanent life policies, including those with LTC riders, well into retirement precisely because the death benefit and care coverage remain useful long after a term policy would have expired.
Recommended
Comments