A1C Under 7.0? How U.S. Diabetics Get Near Standard Life Rates
Yes, most people with diabetes can get life insurance. The real question isn’t eligibility, it’s price and policy type, and both hinge on your A1C control, whether you use insulin, and any complications like kidney or heart disease. Gather your recent labs and medication history before you apply. That paperwork, more than your diagnosis itself, decides what you pay.
TL;DR:
Well-controlled Type 2 diabetics with an A1C under 7.0 often qualify for standard or standard plus rates, sometimes matching non-diabetic premiums.
Type 1 diabetics usually receive table ratings that add 50% to 100% to the premium, depending on complications and disease management.
Underwriters assess multiple factors, including age at diagnosis, insulin dependence, complications, BMI, and recent health data, not diagnosis alone.
Choosing the right policy type and working with an independent agent can significantly improve approval chances and reduce costs.
Preparing comprehensive documentation and stabilizing health metrics six to twelve months before applying can lead to better underwriting outcomes.
Table of Contents
Can People With Type 1 or Type 2 Diabetes Get Life Insurance?
Both Type 1 and Type 2 diabetics can typically buy life insurance, but the paths diverge fast once underwriters start reading your chart. Type 2 diabetics, especially those diagnosed later in life with stable control, often land in Standard or even Standard Plus rate classes. Type 1 diabetics face a tougher road structurally, since the condition usually starts earlier and requires lifelong insulin management, which underwriters weigh more heavily.
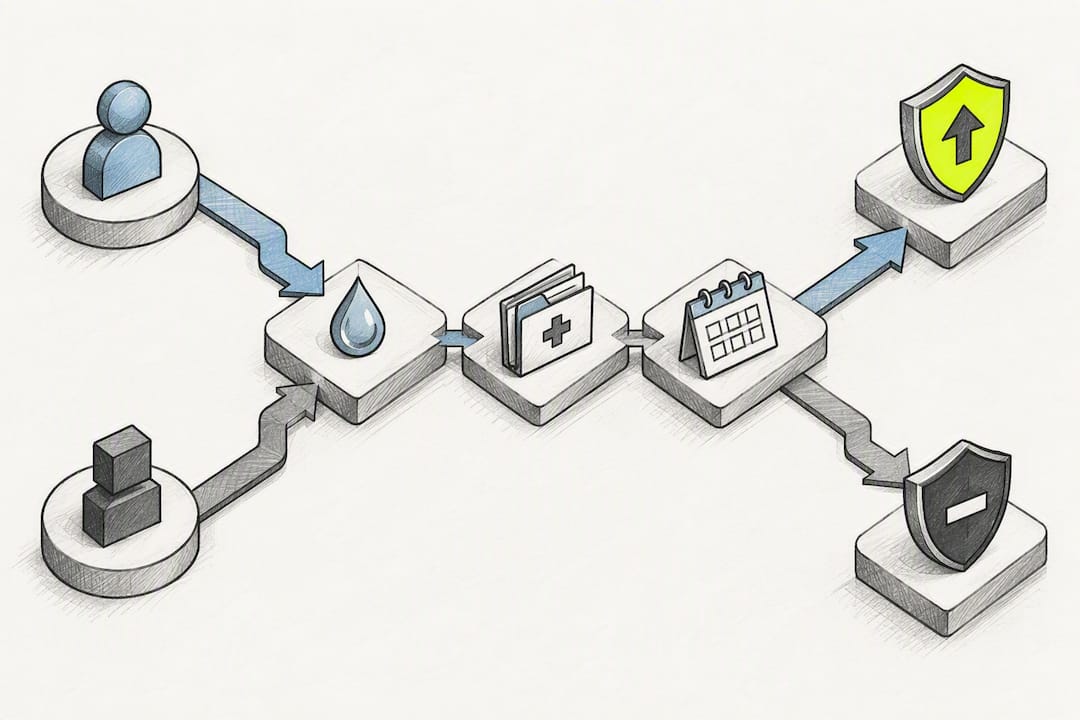
That doesn’t mean Type 1 applicants get shut out. It means they more commonly receive a table rating, a rate class above Standard that adds a percentage to the base premium rather than an outright denial. MoneyGeek’s analysis confirms this pattern: well-managed Type 2 cases frequently clear Standard Plus, while Type 1 cases more often settle into table-rated territory.
Three variables move the needle more than the diagnosis label itself:
Age at diagnosis: Diabetes diagnosed at 45 reads differently to an underwriter than diabetes diagnosed at 12, even at the same current A1C.
Insulin dependence: Needing insulin signals more advanced disease progression to most carriers, regardless of type.
Complications: Neuropathy, retinopathy, or kidney involvement can shift you into a materially higher risk class or trigger further review.
None of these factors are disqualifying on their own. They’re inputs that determine which of several dozen possible rate classes you land in, and that range is wider than most applicants assume.
How Insurers Evaluate Diabetes: A1C, Medications, and Complications
Underwriters build your risk profile from a handful of concrete data points, and A1C sits at the top of that list. The American Diabetes Association defines A1C as a measure of average blood sugar over roughly three months, and most carriers sort applicants into bands based on it.
A1C under 7.0: Generally the sweet spot for better rate classes, often Standard or Standard Plus.
A1C between 7.0 and 7.5: Usually still insurable, though you may see a modest rate bump or a Standard classification instead of Preferred.
A1C above 9.0: Signals poor control and typically pushes applicants into table ratings or, in severe cases, a decline.
A1C bands don’t work in isolation. A 38-year-old with an A1C of 7.2 and no complications will usually underwrite better than a 60-year-old with the same A1C and early kidney changes. Underwriters read the whole file, not one number.
Insulin use matters too, but less than people expect if control is documented and stable. What raises more concern is a recent change in dosing or a hospitalization tied to blood sugar swings. Complications carry real weight: cardiovascular disease, chronic kidney disease, and neuropathy each independently raise perceived mortality risk, a pattern the CDC’s population health research ties to long-term outcomes in poorly controlled diabetes.
Beyond diabetes-specific markers, underwriters also pull BMI, blood pressure, smoking status, and any recent hospitalizations. Expect them to request A1C lab reports, a medication list, and physician notes covering the last one to two years. Notably, MoneyGeek reports that many insurers no longer automatically decline applicants taking GLP-1 medications like semaglutide, provided A1C and overall control show improvement.
Term, Whole, Universal, or No-Exam: Which Policy Fits?
The policy type you choose changes your odds and your monthly bill more than most applicants realize. Here’s how the main options stack up for diabetics specifically:
Term life insurance. The most affordable route for diabetics with reasonably controlled A1C, and the most common recommendation for pure income-replacement needs. Terms of 10, 20, or 30 years are available, though carriers may cap term length for older applicants with complications.
Whole and universal life insurance. These permanent policies cost more upfront but build cash value over time and never expire as long as premiums are paid. Some diabetics use whole life specifically for its guarantees and its role in strategies like Infinite Banking, where the policy’s cash value becomes a source of accessible capital. Indexed universal life offers similar permanence with more flexible premiums, though returns depend on index performance.
Simplified issue policies. No medical exam, just a health questionnaire, with approval often in days instead of weeks. The tradeoff is higher premiums and lower coverage caps, usually in the tens of thousands rather than hundreds of thousands.
Guaranteed issue life insurance. No health questions at all, but coverage amounts are small (often $25,000 or less) and most policies carry a graded death benefit, meaning beneficiaries get less than the full amount if death occurs in the first two to three years, per Western & Southern.
Pro Tip: Don’t default to simplified or guaranteed issue just because your diabetes diagnosis makes traditional underwriting feel intimidating. Full underwriting almost always costs less per dollar of coverage if your A1C is stable, even with a table rating attached.
What Does Life Insurance Cost for People With Diabetes?
Premiums for diabetics vary more by rate class than by the diagnosis itself, which is exactly why two people with the same condition can get very different quotes. Age, sex, coverage amount, and term length set the baseline; your rate class then multiplies from there.
For context, MoneyGeek’s sample pricing on a $500,000, 20 year term policy shows well-controlled Type 2 applicants with A1C under 7.0 landing close to standard non-diabetic rates, while Type 1 applicants with the same coverage amount more commonly see table-rated premiums running noticeably higher per month.
Table ratings work on a fairly simple structure worth understanding before you shop:
Each table level typically adds roughly one quarter more to the base premium, based on general industry data.
A Table 2 rating might mean roughly 50% above standard rates; Table 4 could mean closer to 100% above standard.
Complications or a recent A1C spike can push you up multiple tables at once.
Carrier variance is the detail most applicants miss entirely. Investopedia’s coverage of diabetic underwriting notes that some insurers run diabetes management programs, like John Hancock’s Aspire program, that can factor documented healthy behaviors into pricing. One carrier’s Table 2 might be another carrier’s Standard. That’s not a minor detail. It’s the single biggest reason to get quotes from multiple carriers instead of accepting the first offer you receive.
How to Improve Your Approval Odds Before You Apply
Preparation changes outcomes here more than in almost any other underwriting category. Insurers reward documented stability, and stability takes paper trails to prove.
Start by collecting these documents before you ever submit an application:
Recent A1C lab reports, ideally showing at least two readings over the past 12 months with dates clearly visible.
A current medication list, including dosages and how long you’ve been on your current regimen.
Physician notes confirming your treatment plan is stable, not recently adjusted.
Hospitalization records, if any, with context on what triggered the visit.
A free MIB report, which shows what past insurers have already recorded about your health history and can help you catch surprises before they derail your application.
On the health side, a few actions reliably move underwriters in your favor:
Six to twelve months of stable A1C readings, ideally under 7.5, before you apply.
Quitting smoking, which stacks on top of diabetes risk and can independently drop you a rate class.
Documented blood pressure control, since hypertension alongside diabetes raises cardiovascular flags.
Never omit your diagnosis on an application. Carriers verify through medical records and the MIB database, and nondisclosure can void a policy entirely at claim time, which defeats the entire purpose of buying coverage. If your case involves complications or a recent A1C spike, an agent experienced in impaired-risk underwriting can often place you with a carrier whose specific guidelines read your file more favorably than a different carrier would.
Why an Independent Agent Matters for Diabetic Applicants
Buying life insurance directly from one carrier’s website works fine if your health history is simple. It works against you if you have diabetes with any complexity, because every carrier underwrites diabetes differently and you have no way to know which one favors your specific profile without shopping around yourself.
An independent agent who specializes in impaired-risk cases solves that comparison problem. Instead of applying blind to one company, the agent reviews your A1C trend, medication history, and any complications, then identifies which carriers are likely to offer the best classification for that exact profile.
East Two West Insurance works this way with diabetic applicants, weighing:
Which carriers currently underwrite Type 1 versus Type 2 diabetes most favorably.
Whether term, whole life, or indexed universal life fits your broader financial goals, not just your health profile.
How permanent policies might factor into longer-term strategies like Infinite Banking, where cash value becomes usable capital over time.
If your situation involves multiple health factors or a past decline, that kind of pre-existing condition guidance is worth reading before you apply anywhere.
The Real Problem With Diabetic Life Insurance Advice
Most guides on this topic treat diabetes as a single risk category, as if a Type 2 applicant with an A1C of 6.4 and a Type 1 applicant with frequent hyperglycemic episodes belong in the same conversation. They don’t, and lumping them together is exactly why so many diabetics assume they’ll get declined before they’ve even requested a quote.
The conventional advice to “just apply and see” also undersells how much preparation changes outcomes. Two applicants with identical A1C numbers can land in different rate classes purely because one showed up with a year of stable labs and physician notes, and the other showed up with a file underwriters had to chase down themselves. That gap is entirely within your control.
If there’s one priority to take from all of this, it’s sequencing: stabilize your numbers, gather your documentation, then shop multiple carriers through someone who already knows which ones treat your profile well. Skipping that order is how people end up either overpaying or wrongly assuming they’re uninsurable.
— Jib Hunt
Get Insurance Options Built Around Your Health Profile, Not a Generic Quote
An independent agent can help compare options across multiple carriers and match your A1C, medication history, and complications to the companies most likely to offer a better rate class for your exact profile.
[
Whether you’re looking at term coverage to protect income, whole life for guarantees and long-term cash value, or indexed universal life with more flexible premiums, the goal is finding the structure that fits your health picture and your financial goals, not just the first policy quote that comes back. For diabetics weighing permanent coverage, whole life policies can also serve as a source of accessible capital over time.
Start by visiting East Two West to talk through your specific numbers and get matched with carriers that fit your case.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
What Is the Best Life Insurance for People With Diabetes?
There’s no single best policy for every diabetic, since the right fit depends on your A1C, complications, and coverage goals. Well-controlled Type 2 applicants often do best shopping term life across multiple carriers to find Standard or Standard Plus rates, per MoneyGeek’s findings, while those with more complex histories may benefit from an agent who specializes in matching impaired-risk profiles to favorable carriers.
Is It Hard for Diabetics to Get Life Insurance?
It’s harder than for someone with no chronic conditions, but it’s rarely impossible. Type 2 diabetics with stable A1C under 7.0 frequently qualify for good rate classes, while Type 1 diabetics or those with complications more often face table ratings rather than outright denial.
Can People With Diabetes Get Life Insurance?
Yes, the vast majority of diabetics, Type 1 and Type 2, can get approved for some form of life insurance. Options range from fully underwritten term or permanent policies for well-controlled cases to simplified issue or guaranteed issue policies for those who don’t qualify through traditional underwriting.
What Does Life Insurance Cost for Someone With Diabetes?
Well-managed Type 2 applicants often pay close to standard non-diabetic rates, while Type 1 applicants with a table rating typically pay noticeably more per month for the same coverage.
Recommended
Comments