Annuity RMD Rules for Retirees: FMV, Form 5498, and a CPA Checklist
Annuities held inside a qualified retirement account, like a traditional IRA or 401(k), are subject to required minimum distribution rules just like any other retirement asset. Nonqualified annuities, bought with after-tax dollars, generally aren’t subject to RMDs during your lifetime. Immediate annuity payments typically count as distributions once they start; deferred annuities don’t count until the payout phase begins. SECURE 2.0 also added a genuinely useful wrinkle: excess income from a qualified annuity can now satisfy RMDs owed on other retirement accounts in many cases.
TL;DR:
Qualified annuities inside IRAs or 401(k)s are subject to RMDs, while nonqualified annuities bought with after-tax dollars usually are not.
The calculation depends on fair market value reported by carriers, using IRS tables, and deadlines are April 1 the year after turning 73, with steep penalties for missed deadlines.
Immediate annuities with qualified money satisfy RMDs right away, but deferred annuities only count once payout begins, affecting timing and compliance strategies.
Excess income from qualified annuities can now offset RMDs on other retirement accounts under SECURE 2.0, especially with the increased QLAC premium cap.
Confirming funding source, requesting annual FMV, and consulting a professional are critical steps to avoid costly mistakes and leverage new rules successfully.
Table of Contents
Which Annuities Actually Trigger RMDs?
The single most common mistake retirees make with annuity RMD rules is assuming all annuities work the same way. They don’t. What matters is where the money came from and what kind of account holds the contract.
A qualified annuity sits inside a tax-deferred retirement account, funded with pre-tax dollars from an IRA, 401(k), 403(b), or 457 plan. Because the money never got taxed going in, the IRS requires it to come out eventually, and RMDs apply the same way they would to a mutual fund sitting in that same IRA.
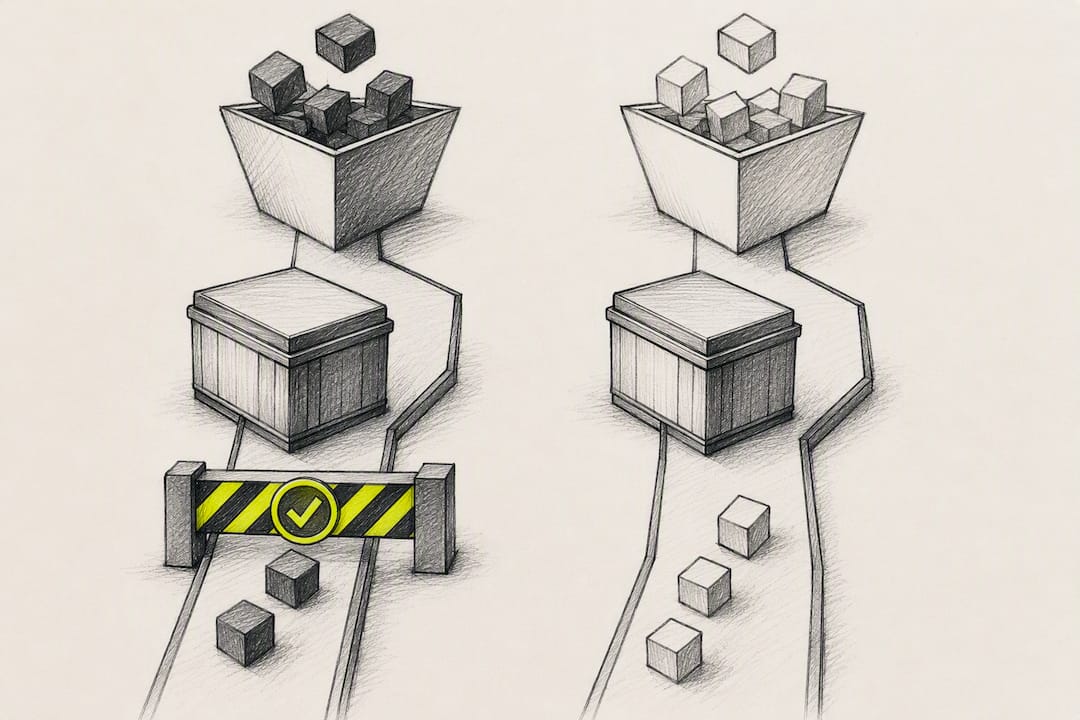
A nonqualified annuity is purchased with money you already paid tax on. There’s no IRS mandate forcing withdrawals during your lifetime because there’s no deferred tax bill waiting to be collected. This distinction trips up a lot of retirees who assume “annuity” automatically means “RMD.”
Roth accounts add another layer. Roth IRAs carry no owner RMDs at all, a rule that hasn’t changed. If you hold an annuity inside a Roth IRA, you can generally leave it alone for as long as you like. That protection disappears for beneficiaries, though. Non-spouse beneficiaries of Roth IRAs still face distribution deadlines, even though the money comes out tax-free. Our breakdown of annuities inside a Roth IRA covers the beneficiary mechanics in more detail.
A few things worth checking on your own paperwork before you assume anything:
Confirm whether your annuity was funded with IRA, 401(k), or after-tax dollars. Carrier statements usually specify this.
Check whether your employer plan has a “still working” exception, which can delay RMDs from a current employer’s 401(k) past age 73 if you haven’t retired.
Verify whether your 403(b) or 457 plan treats pre-1987 contributions differently. Older accumulations sometimes carry separate rules.
Ask your carrier directly if the contract paperwork doesn’t clearly state the funding source. It’s a five-minute phone call that prevents a costly mistake.
For a deeper look at how the qualified and nonqualified distinction plays out at tax time, our guide on qualified versus nonqualified annuities walks through specific scenarios.
How Do You Calculate the RMD on an Annuity?
RMD math starts with one number: the fair market value of the account as of December 31 of the prior year. For annuities, carriers calculate this using actuarial assumptions about the contract’s guarantees, and they typically report it on Form 5498.
Once you have that figure, you divide it by a distribution period pulled from an IRS life expectancy table. Which table applies depends on your situation:
Uniform Lifetime Table applies to most account owners taking RMDs during their own lifetime.
Joint Life and Last Survivor Table applies if your spouse is more than 10 years younger and is the sole beneficiary.
Single Life Table applies to certain beneficiaries of inherited accounts, depending on the beneficiary category.
The IRS publishes the actual worksheets and denominators you need to run this calculation correctly, and they’re worth bookmarking every year rather than relying on memory.
Timing matters as much as the math. Your required beginning date is currently April 1 of the year after you turn 73. That first year gives you a choice: take the distribution by that April 1 deadline, or take it by December 31 of the same year you turn 73. Every year after that, the deadline is simply December 31, no grace period.
Miss the deadline, and the penalty is steep. The IRS imposes a substantial excise tax on the amount you should have withdrawn but didn’t. That’s not a typo. It’s one of the harshest penalties anywhere in the tax code, and it applies automatically unless you catch it.
There’s a partial escape hatch. If you correct the missed RMD within the correction window and file the appropriate form, the excise tax can drop from 25% down to 10%. Documentation matters here. Keep records showing when you discovered the error, when you took the corrective distribution, and the paperwork you filed to request the reduced penalty.
Do Immediate and Deferred Annuities Count Differently Toward RMDs?
Timing is everything, and the type of annuity you own determines when, or whether, its payments count.
A single premium immediate annuity (SPIA) funded with qualified money starts paying out right away, and those payments generally satisfy the RMD for that contract as soon as they begin. According to Stan The Annuity Man’s analysis of immediate annuity RMD treatment, this makes SPIAs one of the simpler RMD-compliance tools available, because the insurer is essentially handling the math for you every year.
Deferred annuities work differently. Until the contract actually starts paying out, it doesn’t generate distributions on its own. That means the account’s FMV still gets added into your RMD calculation for other assets, and you’re on the hook for taking money out of somewhere, whether that’s the annuity itself (via a partial withdrawal) or another IRA, until the payout phase kicks in.
A few contract features change this picture further:
Guaranteed periods and refund features can affect how the annuity’s value gets treated for FMV purposes, since insurers factor those guarantees into the actuarial calculation.
Guaranteed lifetime withdrawal benefits (GLWBs) sometimes let you take RMD-satisfying withdrawals without triggering surrender charges, which is worth confirming with your carrier.
Qualified longevity annuity contracts (QLACs) are the biggest exception of all, and they get their own section below because the rules changed significantly under SECURE 2.0.
Pro Tip: If you’re holding a deferred annuity and haven’t annuitized it yet, ask your carrier for the exact FMV every December, not just when you think you’ll need it. Some carriers only generate this figure once a year, and requesting it late can leave you scrambling before the December 31 deadline.
What Did SECURE 2.0 Change for Annuity RMDs and QLACs?
SECURE 2.0 handed retirees a genuinely practical tool: the ability to apply excess qualified annuity income toward RMDs owed on other aggregated retirement accounts. Before this change, each account’s RMD lived in its own silo. Now, if your qualified income annuity pays out more than its own calculated RMD requires, that excess can offset RMDs due on other qualifying IRAs you own.
The practical effect is straightforward: retirees who structured a qualified income annuity for guaranteed lifetime cash flow no longer have to worry that the “extra” income above their annuity’s own RMD is wasted from a compliance standpoint. It can now count toward the rest of the IRA aggregation group.
QLACs got their own upgrade too. A qualified longevity annuity contract lets you exclude a portion of your IRA or 401(k) balance from RMD calculations entirely, deferring income as late as age 85. The final regulations implementing SECURE 2.0 raised the maximum QLAC premium cap through indexing, meaning retirees can now shelter more of their nest egg using this strategy than the original statutory limit allowed.
A few practical notes on documentation:
Aggregation rules for excess annuity income generally apply within the same account type. IRAs aggregate with IRAs; workplace plans like 401(k)s typically don’t aggregate with IRAs or with each other.
Keep the annual statement from your annuity carrier that shows the actual payment received versus the calculated RMD for that contract. That gap is what you’re applying elsewhere.
403(b) and 457 plans have their own aggregation quirks that differ from IRA rules, so don’t assume workplace plan treatment mirrors IRA treatment.
The IRS is still clarifying some implementation details around how this aggregation interacts with mixed account types, so this is genuinely a “call your CPA before you rely on it” situation rather than a do-it-yourself judgment call.
Where Does the Annuity’s FMV Number Actually Come From?
Every RMD calculation depends on one figure you didn’t calculate yourself: the fair market value your carrier reports. Understanding how that number gets built helps you catch errors before they become IRS problems.
Insurance carriers calculate FMV using actuarial assumptions specific to your contract, factoring in guaranteed income riders, death benefits, and any remaining surrender charge periods. That figure typically shows up on Form 5498, the same form your IRA custodian uses to report other IRA information to the IRS.
Here’s the practical sequence for using it correctly:
Request or locate your carrier’s FMV statement, which usually arrives in January covering the prior December 31 value.
Plug that number into your RMD formula alongside the correct IRS distribution period for your age and beneficiary situation.
If your carrier’s statement is late, delayed FMV reporting is common with complex riders, so call the carrier directly rather than guessing at a number.
If the FMV looks wrong (a sudden jump or drop that doesn’t match your account activity), request a written explanation of the actuarial assumptions behind it before you dispute it with your IRA custodian.
Keep every annual statement your carrier sends, even after you’ve used the number. If a future audit or correction requires you to prove what your RMD should have been in a given year, that paper trail is what backs up your calculation.
Your Annual RMD Checklist for Annuity Owners
Running this process every year, ideally starting in November, keeps you ahead of the December 31 deadline instead of scrambling against it.
Gather your documents. Pull Form 5498, your annuity carrier’s annual statement, and last year’s FMV figures for every qualified account you own.
Calculate the RMD. Apply the correct IRS life expectancy table to each account’s prior year-end value, and aggregate IRAs together where the rules allow it.
Check what your annuity payments already covered. Compare payments received against the calculated RMD for that specific contract, and note any excess that might offset other account RMDs under SECURE 2.0.
Close the gap before December 31. If you’re short, take an additional distribution from another qualified account. If you’ve already missed a prior year’s RMD, follow the IRS correction process and document every step.
Pro Tip: Set a calendar reminder for the first week of November, not December. Carriers get flooded with FMV and distribution requests in the final weeks of the year, and processing delays are common right when you can least afford them.
When your situation involves multiple annuity types, an inherited account, or a QLAC interacting with other IRAs, that’s the point to loop in a CPA or a licensed annuity specialist rather than guessing.
A Practitioner’s Look at How This Plays Out in Real Accounts
A practitioner works with retirees navigating exactly this kind of account-level detail, where the Infinite Banking Concept and traditional annuity strategy both intersect with tax-qualified planning.
Here’s a simplified version of how the SECURE 2.0 excess-income rule plays out in practice. Say a retiree’s deferred income annuity, funded with IRA money, calculates to an RMD of $8,000 for the year but the contract actually pays out $11,000 because of how the income rider was structured. That $3,000 excess can potentially apply toward the RMD owed on a separate traditional IRA the same retiree holds elsewhere, assuming the aggregation rules for that account type are met.
A few situations where a tailored illustration or consultation makes sense:
You hold annuities across multiple account types (IRA, 401(k), and nonqualified) and aren’t sure how aggregation applies.
You’re considering a QLAC purchase and want to model the higher premium cap against your specific balance.
You’ve inherited an annuity and need clarity on spousal versus non-spousal distribution timelines.
Your carrier’s FMV reporting doesn’t match your own recordkeeping.
Specific licensing details and case examples for your situation are best confirmed directly with a consultation.
Why the Conventional Advice on Annuity RMDs Falls Short
Most retirement content treats annuity RMDs as a single rule to memorize. That’s the wrong frame. The real skill is knowing which of four or five distinct scenarios you’re actually in, qualified versus nonqualified, immediate versus deferred, QLAC versus standard deferred, because each one changes the calculation entirely.
What’s underrated is how much power SECURE 2.0’s excess-income provision hands to retirees who structured income annuities well before the rule existed. Nobody designed those contracts anticipating this flexibility, yet it’s available retroactively to anyone whose payments already exceed the contract’s own RMD. That’s worth checking even if you assumed your annuity strategy was already locked in.
What I’d prioritize first: don’t wait until November to find out what your carrier’s FMV reporting actually looks like. The biggest compliance failures I see aren’t calculation errors. They’re timing failures caused by retirees assuming a statement will arrive when it doesn’t. Call your carrier now, not later.
— Jib Hunt
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
Do RMD rules apply to annuities?
Yes, if the annuity is held inside a qualified retirement account like a traditional IRA or 401(k). Nonqualified annuities purchased with after-tax money generally aren’t subject to RMDs during the owner’s lifetime.
How can I reduce federal tax on an annuity withdrawal?
You can’t avoid tax on the taxable portion of a qualified annuity distribution, but Publication 575 outlines methods like the Simplified Method for calculating the tax-free portion of certain annuity payments, which can lower your taxable amount if part of your contract was funded with after-tax dollars.
What is the required minimum distribution for an annuity?
It’s calculated by dividing the annuity’s fair market value as of December 31 of the prior year by a distribution period from the appropriate IRS life expectancy table, based on your age and beneficiary situation.
What are the RMD rules for 2026?
The required beginning date remains age 73, with deadlines of December 31 each year after your first required distribution. SECURE 2.0’s excess qualified annuity income provision and the increased QLAC premium cap both remain in effect, giving retirees more flexibility in how annuity income applies toward RMDs.
Recommended
Comments