Advisors: Save $5,790 by Laddering Multiple Life Insurance Policies
Yes, you can legally own more than one life insurance policy, and insurers underwrite them separately rather than treating it as fraud. The catch is that carriers check your total coverage against your income and existing policies, so stacking too much invites a decline or a request for financial paperwork. Multiple policies work best when they’re matched to distinct obligations, an affordable budget, and full disclosure to every insurer involved.
TL;DR:
Insurers check your total coverage against your income and existing policies, and exceeding typical limits can lead to declines or additional financial disclosures.
Laddered policies, combining different term lengths, are cost-effective because shorter terms are cheaper and match specific obligations like mortgages and children’s education.
Mixing term, whole life, and IUL policies allows tailoring coverage to temporary needs, cash value growth, and long-term cash flow, with proper design avoiding MEC status.
Maintaining a detailed record of all policies, beneficiaries, and ownership structures helps manage multiple policies and prevent oversight or legal complications.
Overfunding permanent policies or owning too many coverage layers can lead to higher premiums and risks of over-insurance, requiring careful coordination and professional advice.
Table of Contents
Why Own More Than One Life Insurance Policy?
Most people who end up with several policies didn’t plan it that way from day one. They bought term coverage in their late 20s, picked up a policy through work, then realized a decade later that a new mortgage or a growing business created a gap the old coverage never anticipated. That’s the real case for layering life insurance: different obligations have different timelines, and one policy rarely fits all of them cleanly.
Laddering works because a mortgage, a child’s college years, and a business loan don’t expire on the same date. Splitting coverage across policies that end when each obligation ends usually costs less than buying one large policy sized for the worst year and holding it for decades.
Time-bound liabilities: a 15-year mortgage and a 20-year child-rearing window rarely align, so separate term lengths match each one precisely.
Distinct financial roles: income replacement, final expenses, and a legacy gift to grandchildren are different jobs, and combining them into one policy makes it harder to size correctly.
Business protection: key-person coverage or a buy-sell agreement funds business continuity and shouldn’t compete with your family’s death benefit.
Employer group life gaps: workplace coverage is usually one to two times salary and disappears the moment you leave the job, which is why it rarely covers a full financial picture on its own.
How Term, Whole Life, and IUL Work Together
Term life is inexpensive, temporary, and built for a specific window. Permanent products like whole life and indexed universal life (IUL) cost more but never expire and build cash value you can access while you’re alive. Most people who own multiple policies mix both types rather than stacking five term policies or five permanent ones.
A term policy with a conversion rider lets you turn some or all of the coverage into permanent insurance later, without new medical underwriting. That matters if your health changes, because it locks in insurability years before you might need it. Riders like waiver of premium or a child rider can also change how a policy behaves without requiring a separate contract.
Term policies handle large, temporary needs cheaply: mortgage payoff, income replacement during working years.
Whole life and IUL build cash value that can supplement retirement income or fund a business need.
A properly designed whole life policy avoids becoming a Modified Endowment Contract (MEC) by staying within seven-pay test funding limits, which preserves tax-favored loan and withdrawal treatment.
Overfunding cash value too quickly is the most common way people accidentally trigger MEC status.
Pro Tip: If you’re adding a permanent policy alongside existing term coverage, ask for an illustration that separates guaranteed cash value from projected dividends. The gap between those two numbers tells you how much of the “growth” is actually promised versus assumed.
What Does a Real Laddering Example Look Like?
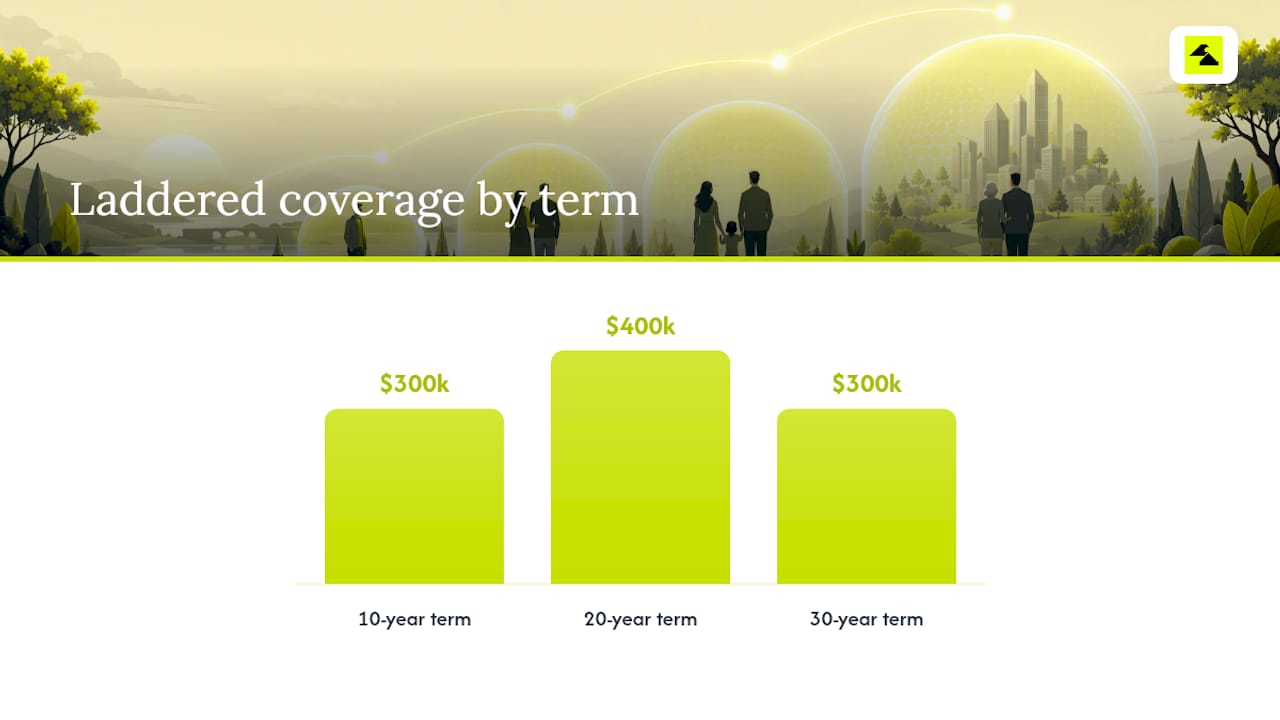
Picture a 35-year-old with a new mortgage, a two-year-old child, and a growing career. Instead of buying one $1,000,000 policy for 30 years, a laddered approach might look like this:
10-year term, $300,000, covering daycare and early childcare costs that disappear once the child starts school.
20-year term, $400,000, sized to the years of private school and college tuition still ahead.
30-year term, $300,000, matched to the mortgage payoff date.
Coverage steps down automatically as each policy expires instead of carrying $1,000,000 in force for three full decades. That difference shows up in the premium. One often-cited example in a NerdWallet cost comparison found a laddered approach totaling roughly $10,470 over the relevant years, versus $16,260 for a single $1,000,000, 30-year term policy written at the same starting age.
That gap exists because term premiums are priced to the length of the level period, and shorter terms are cheaper per dollar of coverage. The example assumes a healthy applicant in a standard rating class; smokers, older applicants, or those with health conditions will see the math shift. Run your own numbers against your actual obligations rather than copying this structure exactly. Someone with no mortgage but a special-needs dependent, for instance, might need the opposite shape: a longer, larger policy and a shorter, smaller one.
How Much Coverage Will Insurers Actually Approve?
Carriers don’t just look at the application in front of them. They pull data on existing coverage and weigh your total exposure against your income, because their real concern is over-insurance, not the number of contracts you hold.
A common underwriting guideline caps total life insurance at roughly 20 to 30 times annual income, though this varies by carrier, age, and how the coverage is justified. Someone earning $150,000 a year might struggle to get approved for $6,000,000 in combined coverage even split across three insurers, because underwriters share data through industry reporting services.
You’re required to disclose all existing and pending life insurance applications when you apply for new coverage.
Insurers often split large amounts across multiple carriers voluntarily, both to diversify company risk and to stay under any single insurer’s internal limits.
Business owners typically need to show financial documentation, tax returns, or a buy-sell agreement to justify coverage tied to a company rather than personal income.
Undisclosed policies discovered during a claim investigation can delay payment or trigger a contestability review, even when the coverage itself was legitimate.
What Do Multiple Policies Actually Cost?
Stacking policies isn’t automatically more expensive than buying one large one, and it isn’t automatically cheaper either. It depends heavily on when each policy was issued and at what age.
A policy purchased at 32 locks in a premium based on your health and age at that moment. Adding a new policy at 45 to cover a fresh obligation doesn’t touch the pricing on the older one; it simply adds a new cost layer priced to your current age and health, which is usually higher per dollar of coverage than what you’re already paying. This is a big part of why keeping an older policy in force, rather than replacing it outright, often saves money over time.
One frequently cited comparison shows a staged, three-policy laddered approach totaling around $10,470, against $16,260 for a single equivalent-value 30-year term policy, illustrating how age-at-issue pricing favors buying smaller policies earlier rather than one large policy later.
Cash-value premiums add another layer: money funding a whole life or IUL policy isn’t available for other goals until it accumulates, so budgeting for permanent coverage means planning around reduced near-term liquidity in exchange for long-term access to cash value. Health changes, occupation risk, and tobacco use all shift your rating class and can make a new policy cost more than an old one for identical coverage.
Should You Keep, Replace, or Add to Existing Coverage?
The single most important operational rule: never cancel an in-force policy until the replacement is fully approved and active. A gap of even a few weeks between canceling old coverage and activating new coverage leaves you completely uninsured if something happens in between.
Replacement can make sense when a new policy offers meaningfully better rates, added riders, or features the old contract lacks. Before replacing anything, check for surrender charges, remaining cash value, and whether the current policy includes guarantees a new one wouldn’t match.
Get the new policy fully underwritten and confirm the effective date in writing.
Compare surrender values and any remaining cash value in the old policy before submitting a cancellation request.
Notify beneficiaries and update recordkeeping only after the new policy is confirmed active.
Cancel the old policy in writing, and keep confirmation of the cancellation date.
Pro Tip: If your current policy was issued years ago at a younger age and lower rating class, replacing it outright rarely beats adding a smaller supplemental policy for the new need.
How Do You Manage Several Policies Without Losing Control?
Owning multiple policies means multiple insurers, multiple account numbers, and multiple beneficiary forms, all of which need to stay coordinated as your life changes.
An irrevocable life insurance trust (ILIT) can own policies on your behalf so proceeds pass outside your taxable estate, which matters more once combined coverage grows large enough to affect estate tax exposure. Individual ownership is simpler for smaller amounts but offers less estate-tax protection.
Keep a single master document listing every policy, carrier, policy number, and beneficiary designation in one place.
Review beneficiary designations after marriage, divorce, or the birth of a child, since outdated forms override your will.
Name contingent beneficiaries on every policy, not just primary ones, to avoid probate delays.
Give your executor or a trusted family member a copy of the document list and claim instructions.
Loop in an estate attorney once combined coverage crosses into estate-tax territory or a trust structure is involved.
What Are the Risks of Owning Too Many Policies?
More coverage isn’t automatically better coverage. Premiums across several policies can quietly outpace your budget, especially when each was added for a good reason but nobody looked at the combined monthly cost.
Multiple simultaneous applications also draw more underwriting scrutiny, since insurers coordinate through shared reporting systems and can flag rapid, layered applications as a possible sign of over-insurance. Cash-value products carry a separate risk: overfunding a whole life or IUL policy can accidentally convert it into a MEC, which strips away favorable tax treatment on loans and withdrawals.
Watch for premium totals creeping past what you’d comfortably pay if your income dropped for a year.
Coordinate applications across carriers so none conflict with disclosed coverage on another application.
Structure permanent policy funding to stay under seven-pay test limits rather than maximizing contributions in early years.
Consider alternatives before adding a new contract: increasing an existing policy’s face amount, converting term to permanent, or funding the goal through savings or an annuity instead.
When Does a Whole Life Policy or Infinite Banking Fit Alongside Term Coverage?
Term coverage handles the big, temporary risk. It doesn’t build cash value, and it doesn’t help once you need liquidity for a business opportunity or want to pass on more than a death benefit. That’s where a properly designed whole life policy earns its place, usually funded heavily through paid-up additions rather than base premium alone, since that’s what drives early cash value and loan capacity.
The Infinite Banking Concept isn’t about replacing term insurance. It’s about giving yourself a place to store and access capital on your own terms, using policy loans instead of a bank, while term coverage still handles the pure protection math.
Dividend expectations should always be shown as non-guaranteed in any illustration, and loan mechanics vary by carrier. Whether Infinite Banking or an IUL belongs in your mix depends on cash flow, not just coverage math.
Is Adding Another Policy Right for You?
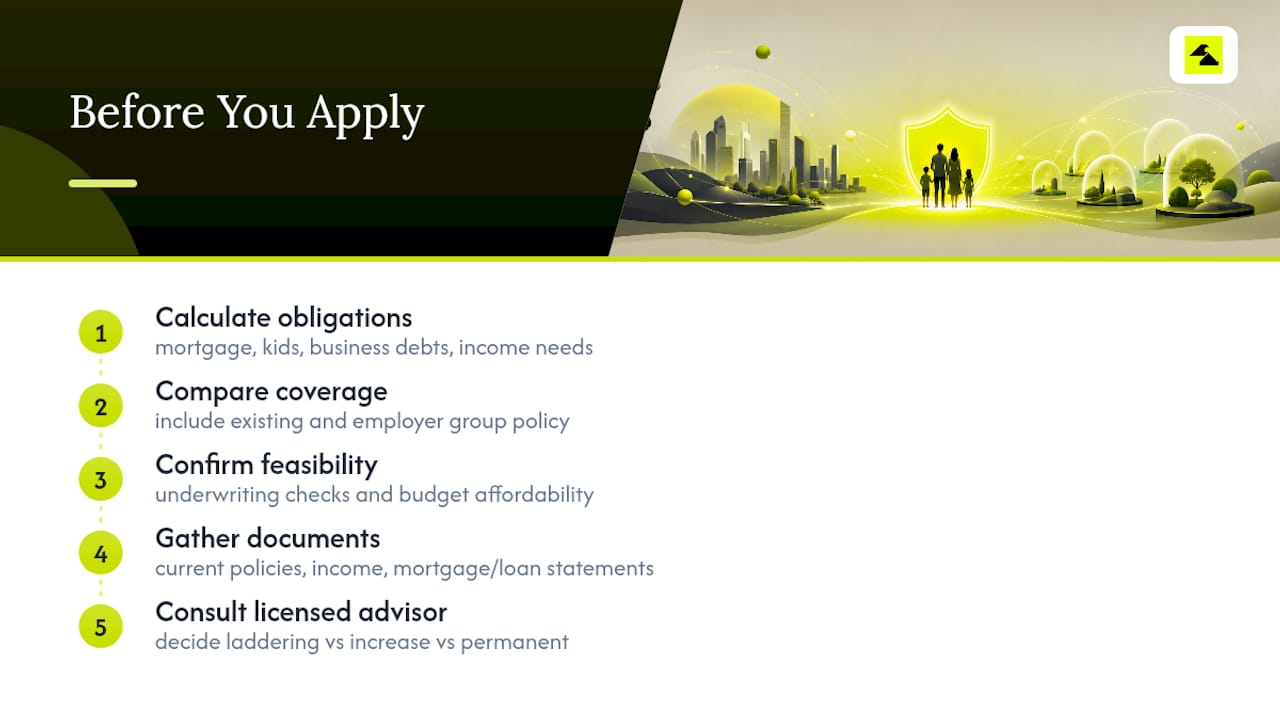
Before applying for anything new, add up your actual obligations: remaining mortgage balance, years until kids are independent, business debts, and income replacement needs. Compare that total against coverage you already have, including any employer group policy.
If underwriting feasibility and budget both check out, a new policy likely makes sense.
Bring current policy statements, income documentation, and mortgage or loan details to a licensed advisor before applying. A quick consultation can confirm whether laddering, a policy increase, or a permanent policy fits your specific numbers better than guessing on your own.
A Practical Note From East Two West
Most people don’t end up with multiple policies through careful design. They end up there through life. Our job is helping clients turn that patchwork into an actual strategy, one built around real cash flow and real goals rather than a generic coverage number.
Infinite Banking gets a lot of attention in our work because it does something term coverage can’t: put capital back in your hands. That said, it isn’t the answer for everyone, and a good advisor should tell you when it isn’t. This article is general education, not personalized advice, so treat it as a starting point for a real conversation.
— Jib Hunt
How East Two West Can Help You Build the Right Coverage Mix
Figuring out the right combination of term, whole life, and IUL takes more than a rate quote. It takes someone comparing your actual obligations against real illustrations, not generic averages. The recommendation isn’t tied to a single company’s product lineup.
[
Whether you’re laddering term policies around a mortgage and college costs, weighing whether a designed whole life policy makes sense for Infinite Banking, or trying to figure out if an old policy is worth keeping, that’s the precise work done daily for business owners, professionals, and families. Replacement analysis, policy design, and quote comparisons across multiple carriers all happen under one roof instead of through separate calls to separate agents.
Visit East Two West to compare quotes or book a consultation and walk through your specific numbers with a licensed professional before you add, replace, or restructure anything.
Sources
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Is It Good to Have Multiple Life Insurance Policies?
It can be, when each policy matches a distinct, time-bound obligation like a mortgage or college costs rather than duplicating coverage you already have. It becomes a problem when total premiums strain your budget or combined coverage exceeds what insurers consider justified by your income.
How Much Does a $1,000,000 Life Insurance Policy Cost per Month?
Cost varies widely by age, health, and term length, with healthy applicants in their 30s typically paying far less per month than older applicants or those with health conditions. Getting quotes across multiple carriers is the only reliable way to see actual pricing for your situation, since no single figure applies to everyone.
What Is the Three-Year Rule for Life Insurance?
The three-year rule generally relates to certain estate-tax provisions where a life insurance policy transferred out of an estate within three years of death can still be included in the taxable estate. Anyone using an ILIT or transferring policy ownership for estate planning should confirm current rules with an estate attorney or tax advisor before relying on this timeline.
Is It Illegal to Take Out Multiple Life Insurance Policies?
No, it’s completely legal to own multiple life insurance policies from the same insurer or different ones. You do have to disclose existing coverage on every new application, and insurers can decline or limit new coverage if your combined total looks disproportionate to your income or need.
How Do I Know if Laddering or a Single Larger Policy Fits Me Better?
Laddering tends to fit predictable, time-limited needs like a mortgage or child-rearing years, while a single larger or permanent policy often suits open-ended goals like legacy planning. A licensed advisor can run both scenarios against your actual numbers, which East Two West offers through a direct consultation or online quote comparison.
Recommended
Comments